Business Life Insurance: Key Uses, Types, and Tax Rules

08-09-2026
Business life insurance is an essential corporate risk management tool that provides financial protection, business continuity, and capital preservation upon the death of an owner, key executive, or employee. Companies utilize these specialized policies to fund buy-sell agreements, offset recruitment costs for vital talent, and secure business loans through collateral assignment.
Running a company means constantly managing financial risk, but few things disrupt an enterprise faster than losing a key decision-maker or partner. When an owner or executive dies unexpectedly, the sudden operational void can stall day-to-day work, rattle lenders, and trigger immediate equity disputes among surviving partners. Securing the right business life insurance setup gives your enterprise an immediate liquid cushion to navigate these exact transitional periods smoothly.
Unlike personal coverage designed to protect a family’s household expenses such as comprehensive family life insurance plans business life insurance policies serve as corporate financial tools structured around organizational survival. A company usually purchases a business life insurance policy on critical personnel, acting as the primary policy owner and beneficiary, or equity holders set up cross-purchase arrangements among themselves. Whether your main goal is protecting revenue from key talent loss, funding partner buyouts, or guaranteeing loan repayment, corporate life and health insurance strategies keep your enterprise stable and preserve baseline valuation.
Core Applications and Business Uses of Life Insurance
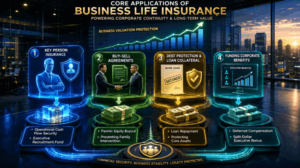
When looking at what are business uses of life insurance, you find several distinct protective strategies built directly into modern commercial risk management. The most common application is key person coverage. Companies buy business life insurance for owners and vital executives whose technical expertise, client relationships, or daily leadership drive revenue. If that designated leader passes away, policy proceeds supply immediate cash to hire high-level recruiters, handle temporary operating losses, and reassure creditors while operations adjust.
Another major operational function involves funding buy-sell agreements among corporate partners. Through cross-purchase or entity-redemption structures, business life insurance policies deliver the exact liquid capital surviving owners need to buy out a deceased partner’s equity from their estate. This setup stops unqualified heirs from stepping into active management, keeps company equity concentrated among active leadership, and ensures the deceased owner’s family receives full market value without forcing anyone to sell off commercial real estate or enterprise assets.
 +-------------------------------------------------------+
| Corporate Policy Structures |
+---------------------------+---------------------------+
|
+-------------------------+-------------------------+
| |
v v
 +-------------------------------------------------------+
| Corporate Policy Structures |
+---------------------------+---------------------------+
|
+-------------------------+-------------------------+
| |
v v
+————————+ +————————+ | Key Person Insurance | | Buy-Sell Agreements | | – Offsets recruitment | | – Funds equity buyout | | – Protects revenue | | – Secures ownership | +————————+ +————————+
Commercial lenders also regularly ask for business owner life insurance as mandatory collateral before approving major credit lines or capital equipment loans. Through a formal collateral assignment, your business life insurance policy guarantees that outstanding corporate debts get paid off automatically if a founder dies, similar to how mortgage protection insurance secures real estate liabilities against unexpected financial hardship.
Structuring Coverage for Small Businesses and Employees
Finding the right small business life insurance requires selecting plans tailored to your team size, equity makeup, and budget goals. For startups and growing firms, offering group term life insurance for small business options gives workers affordable baseline protection as part of standard compensation packages. Providing small business life insurance for employees boosts retention and competitive hiring appeal while keeping overall employer premiums completely manageable.
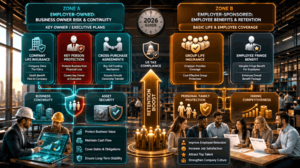
To understand how employer life insurance work does, you need to separate corporate-owned risk protection from employee fringe benefits. In standard group arrangements, companies pay premiums, so staff members receive coverage equal to a multiplier of their salary, with employees naming their own personal beneficiaries. On the other hand, when setting up company life insurance or company insurance life coverage for key owners, the enterprise stays as the owner and beneficiary to cover financial liabilities.
For senior executive teams, business owner life insurance for owners can be tied into executive compensation plans like split-dollar or non-qualified deferred compensation arrangements. Enterprise planners often weigh various structures such as comparing whole life vs term life insurance or utilize permanent solutions like an index universal life insurance policy or single premium whole life insurance to build accessible liquidity. Furthermore, some corporations leverage cash value strategies akin to infinite banking to deliver real long-term financial security to top executives while keeping overall company liquidity intact.
Tax Deductibility and Financial Classifications
A top question for business owners and financial managers working with RGP Agency is whether premiums for life insurance are tax deductible under United States Internal Revenue Code (IRC) rules. Under IRC Section 264, if your company is a direct or indirect beneficiary on a business life insurance policy, those premium payments cannot be deducted as standard business expenses. So, asking is life insurance a business expense or can life insurance be a business expense brings a straightforward answer: it records on balance sheets as a corporate financial commitment, but premiums will not lower your taxable business income.
Key-Person & Owner Policies: Premium payments on company life insurance where the business is the listed beneficiary are non-deductible. However, the resulting death benefits are generally received tax-free under IRC Section 101(a), as long as you comply with notice and consent standards under Section 101(j).
Group Life Insurance: Premiums paid by employers for basic employee group insurance life plans (up to $50,000 per worker) are fully deductible as employee benefit expenses under IRC Section 79, while remaining tax-free for the workers.
Executive Bonus Setup (Section 162): When a firm pays premiums on individual policies owned directly by key employees, those payments are tax-deductible for the business as compensation, and the employee reports the premium amount as income.
Working with an experienced team to review business life insurance quotes helps ensure your corporate policies match both liability needs and IRS compliance guidelines. While base premium payments for corporate-beneficiary coverage offer no immediate tax deduction, the tax-free payout creates an invaluable financial safety net when an unexpected transition hits.
Real-World Application: Executive Transition and Debt Security
Take a growing manufacturing firm with three equal partners and $3,000,000 in commercial machinery debt. The owners set up a cross-purchase buy-sell agreement backed by individual business owner life insurance policies worth $1,500,000 per partner, along with a $2,000,000 key person policy on their lead engineer.
When the lead engineer passed away unexpectedly right before a major production run, the business faced severe delay risks. The key-person death benefit provided $2,000,000 in immediate, tax-free cash reserves. That capital allowed the surviving team to engage executive recruiters, bring in interim technical consultants, and cover contract delays without touching operating cash flow or drawing down credit lines.
Two years later, when one of the senior partners passed away, the surviving owners used the $1,500,000 insurance proceeds to buy the deceased partner’s shares directly from their estate. The transaction closed within 60 days, giving the family fair market liquidity while keeping full ownership and control with the active partners without taking on new debt or selling company assets.
Frequently Asked Questions
What is the main difference between personal and business life insurance?
Personal life insurance protects an individual’s family against income loss, while a business life insurance policy is owned by or structured around a business to fund buy-sell agreements, secure commercial debt, or replace key leadership talent.
Are business life insurance quotes higher than personal policy quotes?
Premiums depend on the insured person’s age, health, tobacco use, and underwriting risk rather than the policy label, though business life insurance policies often feature higher coverage amounts to match enterprise valuations.
How does key person insurance differ from group life insurance for small business options?
Key person insurance protects the business entity against financial losses caused by losing a critical executive, while group life insurance for small business plans serve as employee benefits that pay out directly to the worker’s family.
Can small business owners deduct premiums paid for business life insurance?
No, under IRS rules, if your business is listed as a direct or indirect beneficiary on a policy, premium payments cannot be deducted as corporate operating expenses.
What compliance steps are required for employer-owned life insurance?
Under IRC Section 101(j), companies must give written notice to employees before issuing policy coverage, obtain their signed consent, and keep detailed annual records to preserve tax-free death benefit status.
Editorial Review & About the Authors
Written & Reviewed By: Pablo Pérez
This article was authored and technically reviewed by Pablo Pérez, senior financial advisor and co-founder of RGP Agency. Led by the husband-and-wife team of Pablo and Genesis Pérez, RGP Agency is a family-devoted, community-centric financial planning organization. Based in Texas, the Pérez family and their team of advocates specialize in crafting wealth preservation, healthcare planning, and legacy protection strategies tailored to individual family dreams and business realities. To learn more about our mission, core values, and licensing, visit our official About Us page.
Corporate Headquarters & Contact Verification
For policy designs, personalized business continuity strategies, or to verify agent credentials, you can contact our registered Texas office directly:
- Office Address: 8376 Davis Blvd, Suite 246, North Richland Hills, TX 76182
- Direct Phone: (817) 973-5255
- Official Website: rgpagency.com
References & Authority Citations
- RGP Agency Editorial Team. (2026). Business Life Insurance, Key Person Protection, and Corporate Ownership Guidelines. RGP Agency Business Protection Series. https://rgpagency.com/life-insurance/
- Internal Revenue Service (IRS). (2024). IRC Section 264: Certain Amounts Paid in Connection with Insurance Contracts. Department of the Treasury. https://www.irs.gov/codes/tax-code-section-264
- Internal Revenue Service (IRS). (2024). IRC Section 101(j): Certain Employer-Owned Life Insurance Contracts. Department of the Treasury. https://www.irs.gov/irb/2009-39_IRB
- U.S. Small Business Administration (SBA). (2025). Key Person Insurance and Buy-Sell Funding Requirements for Business Debt Financing. U.S. Small Business Administration. https://www.sba.gov
- National Association of Insurance Commissioners (NAIC). (2024). Commercial Life Insurance and Business Succession Valuation Protocols. NAIC Market Regulation Standards. https://content.naic.org
Social Share

Life Insurance
Protect your family’s future.


Health Insurance
Stay healthy, stay protected.

Income Annuities
Turn savings into steady income.

