Final Expense Life Insurance for Seniors: Best Plans

09-09-2026
Final expense life insurance for seniors is a specialized form of permanent whole life coverage designed to pay cash benefits directly to beneficiaries to cover funeral costs, medical bills, and remaining legal obligations upon the insured’s passing. Typically issued in benefit amounts ranging from $5,000 to $50,000, these policies feature level premiums, guaranteed cash value accumulation, and simplified medical underwriting without required physical exams.
Planning for end-of-life expenses requires an understanding of how burial insurance contracts function relative to standard term or permanent policies. For adult children researching final expense life insurance for seniors, choosing an appropriate policy protects family finances from sudden funeral expenses and unpaid medical bills.
Navigating carrier options, underwriting tiers, and rate structures enables families to select coverage that matches their budget. Evaluating simplified issue and guaranteed issue life insurance policies allows seniors to secure immediate or graded protection regardless of past health conditions.
Defining Final Expense Whole Life Insurance and Coverage Mechanics
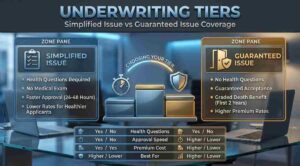
Understanding final expense life insurance for seniors requires examining its underlying structure as a permanent whole life contract. Unlike temporary term policies that expire after a set duration, final expense policies remain active for the insured’s entire lifetime, provided premium payments are maintained according to the contract schedule.
When purchasing a best final expense insurance plan, the selected benefit amount locks in alongside a fixed monthly premium rate. The insurance carrier guarantees that monthly premium rates will never increase due to advancing age or deteriorating health, providing budget stability for seniors living on fixed retirement incomes.
Upon the policyholder’s death, the carrier pays out the tax-free death benefit directly to designated beneficiaries. Beneficiaries retain complete flexibility over how funds are spent, utilizing the proceeds to cover funeral service fees, burial or cremation costs, outstanding hospital balances, credit card balances, or probate legal fees.
Underwriting Tiers: Simplified Issue vs Guaranteed Issue Coverage
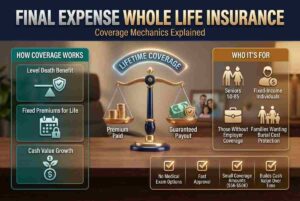
Evaluating final expense life insurance carriers involves distinguishing between simplified issue and guaranteed issue underwriting designs. Simplified issue policies require applicants to answer basic medical health history questions but eliminate physical medical exams, blood draws, and physician visits.
Simplified issue contracts offer immediate coverage starting on day one for applicants who meet basic underwriting criteria. Conversely, guaranteed issue final expense life insurance requires zero health questions and guarantees approval for all qualifying applicants within eligible age brackets, typically ages 50 to 85.
+-------------------------------------------------------------------------+
|                Final Expense Underwriting Comparison                    |
+-------------------------------------------------------------------------+
| Simplified Issue ---> Basic Health Questions | Day-One Full Coverage    |
| Guaranteed Issue ---> No Health Questions    | 2-Year Graded Waiting    |
+-------------------------------------------------------------------------+
Guaranteed issue coverage includes a contractual two-year graded benefit period. If the insured passes away from natural causes during the first two policy years, the carrier returns all paid premiums plus an interest percentage (typically 10%) rather than paying the full face value. Full death benefits apply immediately if death results from an accidental injury during the initial period.
Cost Determinants, Rate Benchmarks, and Carrier Reviews
Analyzing final expense life insurance cost metrics reveals that premium pricing depends primarily on issue age, biological sex, smoking status, and face value coverage amounts. Because mortality risk rises statistically with age, securing coverage earlier yields lower monthly premium quotes.
Average monthly costs for a $10,000 simplified issue policy illustrate typical market rates across senior age demographics:
A 60-year-old non-smoking female pays approximately $30 to $40 monthly.
A 60-year-old non-smoking male pays approximately $40 to $50 monthly.
A 70-year-old non-smoking female pays approximately $50 to $65 monthly.
A 70-year-old non-smoking male pays approximately $65 to $85 monthly.
Reviewing final expense insurance reviews requires analyzing carrier balance sheets and customer service ratings. Established providers like Globe Life or Northwestern Mutual offer different coverage structures; for instance, Globe Life offers step-rate term options that increase in cost every five years, whereas traditional mutual providers focus on level-premium permanent best whole life insurance coverage.
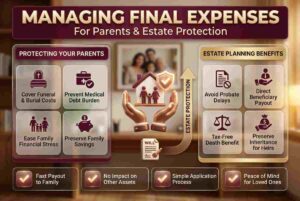
Managing Final Expenses for Parents and Estate Protection
Purchasing final expense life insurance for parents allows adult children to prevent unexpected out-of-pocket costs during times of bereavement. The average cost of a traditional adult funeral featuring burial, viewing, and vault installation often exceeds $10,000, creating financial pressure if liquid cash reserves are unavailable.
Adult children can serve as policy owners and pay monthly premiums on behalf of aging parents, provided the parent consents and participates in the application process. Setting up automatic premium payments ensures the policy remains active and avoids policy lapses that could forfeit built-up cash values.
Additionally, permanent life insurance policies build a modest cash value account over time through guaranteed interest compounding. Policyholders can access this cash value during emergencies via policy loans, providing secondary liquidity while maintaining base protection.
Strategic Policy Selection and Rate Optimization
Obtaining competitive final expense life insurance quotes requires comparing rates across multiple independent carriers rather than relying on a single captive provider. Independent specialists at RGP Agency compare prices across dozens of carriers to match specialized health conditions such as diabetes, hypertension, or past cardiac events with favorable underwriting guidelines.
Selecting an appropriate face value requires calculating immediate end-of-life obligations. Factoring in funeral arrangements, cemetery plot purchases, outstanding medical copays, and short-term personal debts helps define an accurate coverage threshold, preventing over-purchasing or under-insuring.
Maintaining accurate beneficiary designations ensures seamless claim processing upon the policyholder’s passing. Naming primary and contingent beneficiaries clearly allows the insurance carrier to disburse claim funds directly to heirs without probate court delays.
Practical Case Study: Funeral Cost Risk Mitigation
Consider a 68-year-old retired widow residing in Texas with moderate health conditions including controlled type 2 diabetes and hypertension. Seeking to ensure her adult children are not burdened by funeral expenses, she applies for a simplified issue policy.
+-------------------------------------------------------------------------+
|                  Sample Final Expense Policy Structure                  |
+-------------------------------------------------------------------------+
| Selected Policy Type:         Simplified Issue Whole Life               |
| Total Coverage Face Amount:    $15,000 Level Death Benefit              |
| Fixed Monthly Premium:        $62.00 (Guaranteed Level for Life)        |
| Underwriting Requirement:     No Physical Exam (Health Questionnaire)   |
| Benefit Availability:         Immediate Day-One Full Coverage           |
+-------------------------------------------------------------------------+
Because her medical conditions are controlled, she qualifies for simplified issue coverage at $62 per month. Three years after policy issuance, she passes away due to natural causes. The insurance carrier processes the claim within seven business days, disbursing $15,000 tax-free directly to her daughter.
The daughter uses $11,500 to settle all funeral and cremation invoices immediately and applies the remaining $3,500 to pay off final medical bills, preserving the family’s personal savings.
Frequently Asked Questions
What is the primary difference between final expense insurance and traditional life insurance?
Final expense insurance is a whole life policy designed specifically for smaller coverage amounts, typically between $2,000 and $50,000. Traditional life and health insurance policies focus on income replacement or mortgage protection insurance and usually require larger face amounts and medical examinations.
Does final expense life insurance require a physical medical examination?
No, final expense life insurance policies do not require physical medical examinations, blood draws, or urine samples. Applicants qualify by answering basic medical history questions or by selecting a guaranteed issue policy that requires no health questions.
Can a policyholder’s monthly premium increase as they get older?
No, final expense whole life policies feature contractually fixed level premiums. Once the policy is issued, the monthly premium rate remains identical for the life of the contract and cannot be increased due to advancing age or health changes.
What happens if a senior passes away during the two-year graded period on a guaranteed issue policy?
If the insured passes away from natural causes during the two-year graded benefit period, the carrier returns all premiums paid up to that point plus an interest percentage (typically 10%). Full death benefits are paid immediately if death is caused by an accident.
Are final expense life insurance benefit payouts subject to federal income taxes?
No, death benefit payouts received by beneficiaries from a final expense life insurance contract are generally exempt from federal income taxes under Internal Revenue Code Section 101(a).
Editorial Review & About the Authors
Written & Reviewed By: Pablo Pérez
This article was authored and technically reviewed by Pablo Pérez, senior financial advisor and co-founder of RGP Agency. Led by the husband-and-wife team of Pablo and Genesis Pérez, RGP Agency is a family-devoted, community-centric financial planning organization. Based in Texas, the Pérez family and their team of advocates specialize in crafting wealth preservation, retirement income security, and senior final expense insurance strategies tailored to individual family dreams and business realities. To learn more about our mission, core values, and state licensing, visit our official About us page.
Corporate Headquarters & Contact Verification
For personalized policy quotes, illustrations, or agent credential verification, contact our registered Texas headquarters directly:
- Office Address: 8376 Davis Blvd, Suite 246, North Richland Hills, TX 76182
- Direct Phone: (817) 973-5255
- Official Website: rgpagency.com
References & Authority Citations
- RGP Agency Editorial Team. (2026). Final Expense Life Insurance & Senior Burial Protection Strategies. RGP Agency Life Series. https://rgpagency.com/life-insurance/final-expense-insurance/
- National Association of Insurance Commissioners (NAIC). (2026). Consumer Guide to Senior Life Insurance and Final Expense Coverage. NAIC Regulatory Standards. https://content.naic.org/
- Internal Revenue Service (IRS). (2026). IRC Section 101(a): Death Benefit Tax Treatment and Life Insurance Proceeds. Department of the Treasury. https://www.irs.gov/
- National Funeral Directors Association (NFDA). (2026). Statistics and Cost Trends for Burial and Cremation Services. NFDA Research Reports. https://nfda.org/
- American Council of Life Insurers (ACLI). (2026). Life Insurance Fact Book: Senior Whole Life and Final Expense Trends. ACLI Industry Reports. https://www.acli.com/
Social Share

Life Insurance
Protect your family’s future.


Health Insurance
Stay healthy, stay protected.

Income Annuities
Turn savings into steady income.

